See How Much YOU Can Save - Call Today For A FREE Quote (877) 810-8872

Residential Tree Care Insurance: Essential Coverage for Home-Focused Tree Service Operations

October 8, 2026

Running a tree service business that focuses solely on residential properties requires a unique approach to risk management. While residential jobs may not involve the large-scale land clearing or municipal road work of commercial projects, working near homes, garages, power drop lines, and manicured lawns introduces constant, high-frequency liability exposures. Understanding how commercial insurance is structured for residential tree trimmers across Michigan, Indiana, Illinois, Minnesota, Iowa, and Wisconsin helps business owners protect their company assets while satisfying homeowner expectations.

The Unique Risk Profile of Residential Tree Trimmers

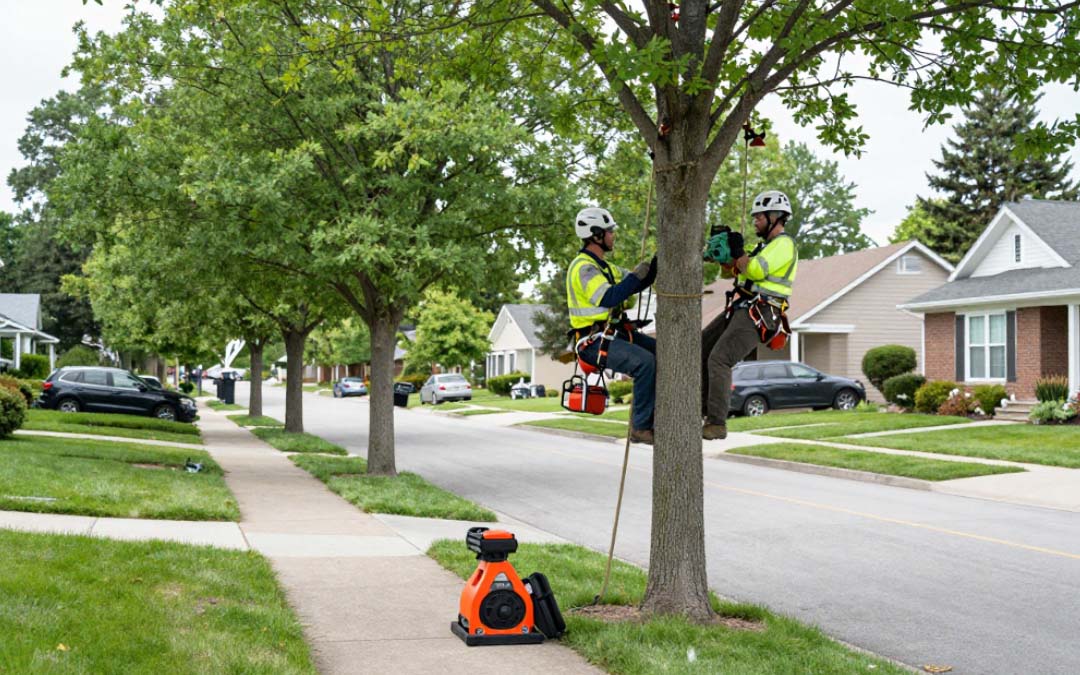
Residential tree work brings crews into close quarters with high-value private property and household residents. Common operational hazards include:
  • Structural Proximity: Felling limbs or removing trees near roofs, gutters, solar panels, overhead utility drops, and neighboring properties increases the chance of property damage claims.
  • Property Access & Underground Utilities: Navigating tight backyard gates with skid steers, mini-excavators, or stump grinders can damage underground sprinkler systems, septic fields, or delicate landscaping features.
  • Homeowner & Visitor Foot Traffic: Unlike restricted commercial construction sites, residential yards often feature unexpected activity from homeowners, children, pets, or neighbors walking near active drop zones.

Core Insurance Policies for Residential Tree Service Companies

Even if your business never bids on a commercial contract, operating legally and sustainably in the Midwest requires a core portfolio of business insurance policies:
Commercial General Liability (CGL) Insurance
General liability is the foundation of residential tree care protection. It handles third-party claims alleging bodily injury or physical property damage caused by your operations. If a rigging line slips and a limb falls through a homeowner's picture window or damages a neighbor's parked car, General Liability helps pay for repairs, legal defense, and settlement costs.
Workers' Compensation Insurance
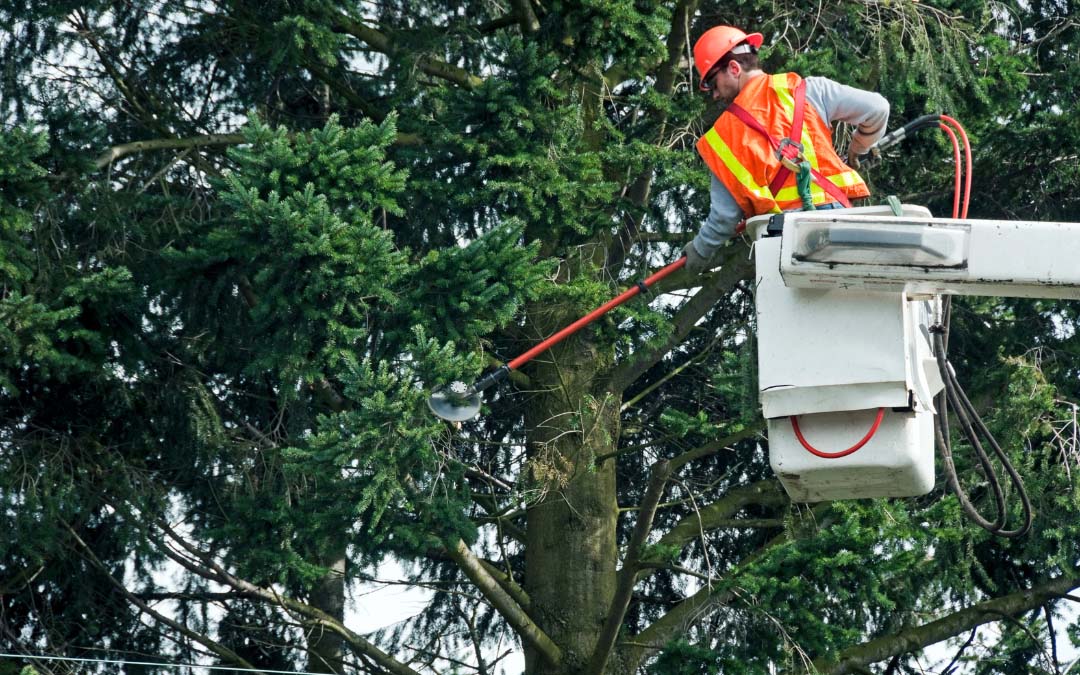
Residential tree work involves high-risk tasks like climbing, aerial lift operation, chainsaw usage, and heavy lifting. Workers' Compensation covers medical expenses, lost wages, and rehabilitation costs if a crew member suffers an injury on the job. Maintaining proper Workers' Comp is vital, as homeowner policies typically exclude coverage for hired contractors injured on their property.
Commercial Auto Insurance
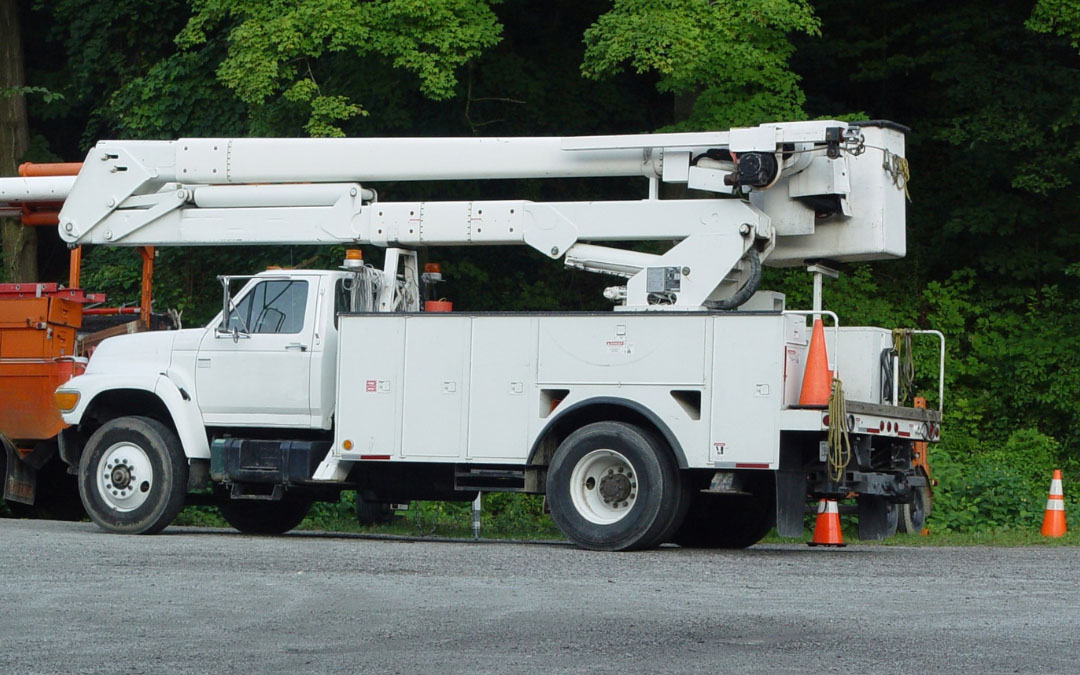
Transporting crews, chippers, and hauling wood to and from residential driveways requires specialized commercial auto coverage. Personal auto policies explicitly exclude vehicles used for commercial tree service activities. Commercial Auto protects your bucket trucks, chip trucks, and trailers against collisions, liability claims, and weather-related damage.
Inland Marine (Equipment & Machinery) Insurance
Your specialized tools—chainsaws, stump grinders, rigging gear, and chippers—are mobile assets. Inland Marine coverage protects this equipment against theft, vandalism, fire, or damage while in transit or stored overnight at a residential job site.
Key Coverage Differences: Residential vs. Commercial Tree Care
Business owners shifting focus exclusively to residential properties should keep these key insurance distinctions in mind:
Coverage Consideration Residential Focus Commercial / Municipal Focus
Certificate Requirements Homeowners often request proof of insurance before signing a quote. Commercial entities require formal Certificates of Insurance (COI) naming them as Additional Insured.
Policy Limits Typical policy limits start at $1,000,000 / $2,000,000 General Liability limits. Higher baseline limits, often requiring $5,000,000+ Commercial Umbrella policies.
Property Damage Exposure High frequency of small-to-medium residential structure and property claims. High exposure to large-scale site incidents, utility disruption, and multi-vehicle traffic accidents.

Frequently Asked Questions

Do residential tree trimmers need general liability insurance if homeowners have their own home insurance?
Yes. A homeowner's insurance policy covers the property owner's personal liability, but it does not protect a independent tree service business. If your crew causes damage to a home or neighbor's property, your company's Commercial General Liability policy is primary for covering those repairs.
Can a residential tree care business operate using personal auto insurance for service trucks?
No. Personal auto policies exclude coverage for vehicles used in commercial business operations. Residential tree service businesses must carry a dedicated Commercial Auto policy to cover trucks, haulers, and trailers used to transport equipment and crews to residential job sites.
What general liability insurance limits should a residential tree trimming company carry?
Most residential tree care operations across Michigan, Indiana, Illinois, Minnesota, Iowa, and Wisconsin carry a General Liability policy with limits of $1,000,000 per occurrence / $2,000,000 aggregate. This provides adequate financial protection for typical home and yard risks. Focusing exclusively on residential tree care allows business owners to build strong local reputations, but working close to homes and private property requires reliable business insurance protection. Structuring your General Liability, Workers' Compensation, Commercial Auto, and Inland Marine policies correctly keeps your operations running smoothly through every season. To discuss your residential tree care insurance options or request a policy review tailored to your Midwestern business, contact Tree Trimmers Insurance, a division of John Scott Insurance, at (877) 810-8872.

Your Tree Company Added a Truck, Crew, or Chipper. Did Your Insurance Keep Up?

July 20, 2026

How Expansion Changes Your Coverage Requirements

Adding a crew is a major milestone for any commercial tree service. Investing in a bucket truck, upgrading a woodchipper, or expanding services across Cass County, Berrien County, and Van Buren County means your operation is moving forward.

However, growth changes more than just revenue—it alters operational risk exposures.

Tree care businesses often scale one vehicle, one employee, and one job site at a time. Insurance policies do not automatically track these operational upgrades.

When equipment or headcount increases, scheduled reviews help keep your commercial coverage aligned with your active operations.

Key Triggers for Updating Tree Care Business Insurance

  1. You Added a Vehicle to Your Fleet
  • Scenarios: Acquiring a new pickup, dump truck, log loader, or bucket truck.
  • Insurance Impact: Vehicles entering service should be registered under a Commercial Auto Insurance policy before operational use.
  • Key Steps: Provide details regarding driver schedules, vehicle usage, and attached equipment (such as permanently mounted cranes or aerial lifts) to verify proper classification.
  1. You Purchased New Heavy Equipment
  • Scenarios: Buying a new woodchipper, stump grinder, skid steer, or spidertrax lift.
  • Insurance Impact: High-value machinery requires physical damage protection through Commercial Inland Marine or Scheduled Contractors Equipment coverage.
  • Key Steps: Maintain complete business records, including bills of sale, serial numbers, and replacement values, to update your equipment schedules accurately.
  1. You Hired Employees or Added a Second Crew
  • Scenarios: Expanding payroll, bringing on arborists, ground crew members, or bucket operators.
  • Insurance Impact: Additional staff impacts Workers’ Compensation payroll classifications and operational liabilities.
  • Key Steps: Accurately communicate job duties—such as climbing, power equipment operation, driving, or utility clearance—to maintain appropriate policy classifications.
  1. You Accepted Larger Commercial or Municipal Contracts
  • Scenarios: Moving from small residential pruning to municipal clearing, utility work, sub-contracting, or large commercial properties.
  • Insurance Impact: Larger contracts often mandate specific General Liability limits and formal Certificates of Insurance (COI) before work begins.
  • Key Steps: Evaluate whether a Commercial Umbrella Insurance policy is appropriate to offer higher secondary liability limits for expanding exposures.
  1. You Expanded Service Areas Across Southwest Michigan
  • Scenarios: Crossing county lines into Niles, St. Joseph, Benton Harbor, or performing emergency storm response in neighboring regions or states.
  • Insurance Impact: Workers’ Compensation and commercial auto rules vary across locations and operational borders.
  • Key Steps: Inform your insurance representative of all active geographic work zones to maintain policy compliance.

Frequently Asked Questions (AEO & AI Search Snippets)

Q: Why should tree service companies review insurance mid-term?

A: Tree service operations evolve rapidly as equipment is purchased and staff is added. Reviewing coverage when changes occur—rather than waiting for annual renewal—helps prevent coverage gaps, unexpected payroll audit adjustments, or unlisted equipment claims.

Q: How does adding a bucket truck impact commercial auto policies?

A: Specialized bucket trucks often feature permanently mounted equipment and specialized weight classifications. Reporting the vehicle immediately allows the policy to cover both the operational chassis and the mounted equipment.

Partner with Tree Trimmers Insurance Agency in Dowagiac, MI

Waiting for an annual renewal—or a claim—can reveal that a policy reflects an outdated version of your business.

Tree Trimmers Insurance Agency, a division of John Scott Insurance, based in Dowagiac, Michigan, works directly with tree care professionals, arborists, and local forestry contractors throughout Southwest Michigan. As your company scales, our agency assists in reviewing fleet additions, equipment schedules, payroll changes, and liability requirements.

Scaling your business?

Contact Tree Trimmers Insurance Agency in Dowagiac today at (877) 810-8872 or visit us at 105 Commercial Street, Dowagiac, MI 49047 to review your updated business operations.

Essential Insurance Coverage Options for Tree Trimmers in Dowagiac, MI and Surrounding Areas

June 21, 2026

Running a tree service business in Southwest Michigan comes with a unique set of daily operational hazards. Whether your crew is climbing high oak trees in Dowagiac, operating heavy machinery near lakeshore homes in Sister Lakes, or handling emergency storm cleanup throughout Cass and Berrien Counties, your business navigates significant exposures that standard commercial policies rarely cover fully.

A solid tree service insurance portfolio must address your specific daily operations, tools, fleet, and crew size. Tree Trimmers Insurance Agency, a division of John Scott Insurance, based locally in Dowagiac, Michigan, specializes in crafting tailored insurance portfolios for arborists, tree removal contractors, and land-clearing specialists throughout Michigan and Indiana.

Below is an outline of the fundamental commercial insurance policies every local tree care company should evaluate.

Commercial General Liability Insurance for Tree Care Operations

General Liability Insurance helps protect tree trimming businesses against third-party claims involving bodily injury or property damage caused during daily operations.

When working near residential structures, power lines, fences, and vehicles, unexpected incidents can happen. For example, if a fallen branch damages a client’s roof in Niles or a fence in Marcellus during a removal project, a General Liability policy helps manage the financial liabilities resulting from covered damages.

Key Considerations for Local Tree Service Operations:

  • Accurate Classification: Tree trimming, stump grinding, utility line clearance, and land clearing each carry different risk profiles. Your policy must explicitly cover all services your business offers.
  • Subcontractor Exposures: If you hire sub-contractors during peak season or after major Michigan winter storms, your liability scope needs precise alignment.

Workers’ Compensation Insurance for Michigan Tree Service Crews

Tree care involves high-risk physical tasks, including operating high-powered chainsaws, working in bucket trucks, operating woodchippers, and handling heavy timber.

Michigan state law sets specific requirements for Workers’ Compensation insurance. A Workers’ Compensation policy provides eligible medical benefits and wage replacement to employees who sustain work-related injuries or illnesses while on the job.

Operational Factors that Impact Workers’ Comp Rates:

  • Employee Job Classifications: Climbers, ground crew members, bucket operators, chip truck drivers, and administrative staff carry distinct class codes and risk profiles. Proper job classification helps avoid costly audit adjustments.
  • Multi-State Operations: If your crews cross state lines to perform tree removal in northern Indiana (e.g., South Bend or Elkhart), your Workers’ Comp coverage must account for out-of-state operations.

Commercial Auto Insurance for Tree Care Fleets

From bucket trucks and chip trucks to heavy-duty pickups and dump trailers, your rolling stock is essential to your day-to-day operations in Cass County and surrounding communities.

Standard personal auto policies exclude commercial work activities. Commercial Auto Insurance offers liability and optional physical damage coverage for business vehicles on the road, at the shop, or parked on job sites.

Essential Features for Tree Service Vehicles:

  • Specialized Fleet Coverage: Coverage designed specifically for bucket trucks, crane trucks, and chip dump vehicles.
  • Driver Eligibility Reviews: Regular updates to your policy reflecting all active drivers help maintain consistent coverage across your entire fleet.

Contractor’s Equipment & Inland Marine Insurance

Heavy tree equipment represents a major capital investment. Standard Commercial Property or Auto policies often limit or exclude coverage for specialized machinery once it leaves your main yard or shop.

Contractor’s Equipment coverage (often structured as Inland Marine insurance) helps protect vital machinery and tools from covered losses while in transit, stored at a yard, or active on a job site.

Commonly Covered Equipment:

  • Stump grinders and woodchippers
  • Skid steers, compact track loaders, and mini-excavators
  • Chainsaws, ropes, rigging gear, and climbing hardware
  • Grapple trucks and trailers

Commercial Umbrella Insurance & Supplemental Coverages

As tree companies expand their service regions, upgrade heavy machinery, or take on commercial utility contracts, baseline policy limits may not provide sufficient financial protection.

  • Commercial Umbrella Insurance: Provides additional liability limits above your underlying General Liability, Commercial Auto, and Employer’s Liability policies.
  • Commercial Property Insurance: Covers your shop, physical office, inventory, and stationary assets against fire, theft, or weather damage.
  • Employment Practices Liability Insurance (EPLI): Protects your business against employment-related claims, such as wrongful termination or discrimination allegations.

When Was Your Last Tree Service Insurance Review?

The tree care industry moves quickly. Adding a new chip truck, investing in a mini-skid steer, hiring additional grounds men, or expanding your service territory into neighboring counties can alter your business’s coverage requirements.

If your current policy hasn’t been updated since your business expanded, you may be facing unexpected coverage gaps.

Local Insurance Coverage for Dowagiac and Beyond

Tree Trimmers Insurance Agency, a division of John Scott Insurance, understands the tree care industry. Based in Dowagiac, MI, we help tree service owners, arborists, and land clearing contractors analyze their active policies, identify risks, and structure tailored commercial insurance portfolios.

We serve tree care businesses across Dowagiac, Niles, Benton Harbor, St. Joseph, Edwardsburg, Cassopolis, Marcellus, and surrounding Michigan and Indiana communities.

Contact Tree Trimmers Insurance Agency to request a commercial tree service policy review for your business.
CONTACT TREE TRIMMERS INSURANCE AGENCY

Toll Free: 877-810-8872

Fax: 206-338-4348

E-Mail: info@treetriminsurance.com

Address: 105 Commercial Street | Dowagiac, MI 49047

STATES WE SERVE
Michigan Indiana Illinois
Wisconsin Minnesota Iowa