See How Much YOU Can Save - Call Today For A FREE Quote (877) 810-8872

Managing Michigan Fall Storm Surge: How Emergency Tree Work Impacts Workers’ Comp & Liability Ratings

September 23, 2026

As summer transitions into fall across Michigan, weather patterns bring high-wind events, severe thunderstorms, and early lake-effect ice events. For arborist businesses operating throughout the state, autumn triggers a surge in high-demand, emergency storm response jobs. At Tree Trimmers Insurance, a division of John Scott Insurance, our agents specialize in helping commercial tree care contractors structure their policies to navigate these high-hazard seasonal workloads effectively.

While rapid-response work increases revenue, operating in high-wind conditions near unstable structures and downed power lines introduces severe operational exposures. Understanding how emergency operations affect your Workers’ Compensation Experience Modification Rating (EMR) and General Liability policy structures helps maintain predictable insurance overhead.

Direct Answer: How Emergency Storm Work Drives Insurance Costs

Emergency tree work increases insurance costs primarily through two mechanisms:

  1. Workers’ Compensation EMR Escalation: Claims resulting from high-severity incidents (e.g., rope failures, chain saw kickbacks, or electrocutions) increase your Mod Factor for three policy years, directly multiplying your base Workers' Comp rate.
  2. General Liability Classification & Payroll Audits: Unplanned overtime and unclassified subcontractor labor during emergency callouts can result in unexpected premium adjustments during annual policy audits.

3 Critical Operational Exposures During Michigan Fall Storm Cleanup

High-Hazard Work Environment & EMR Impact

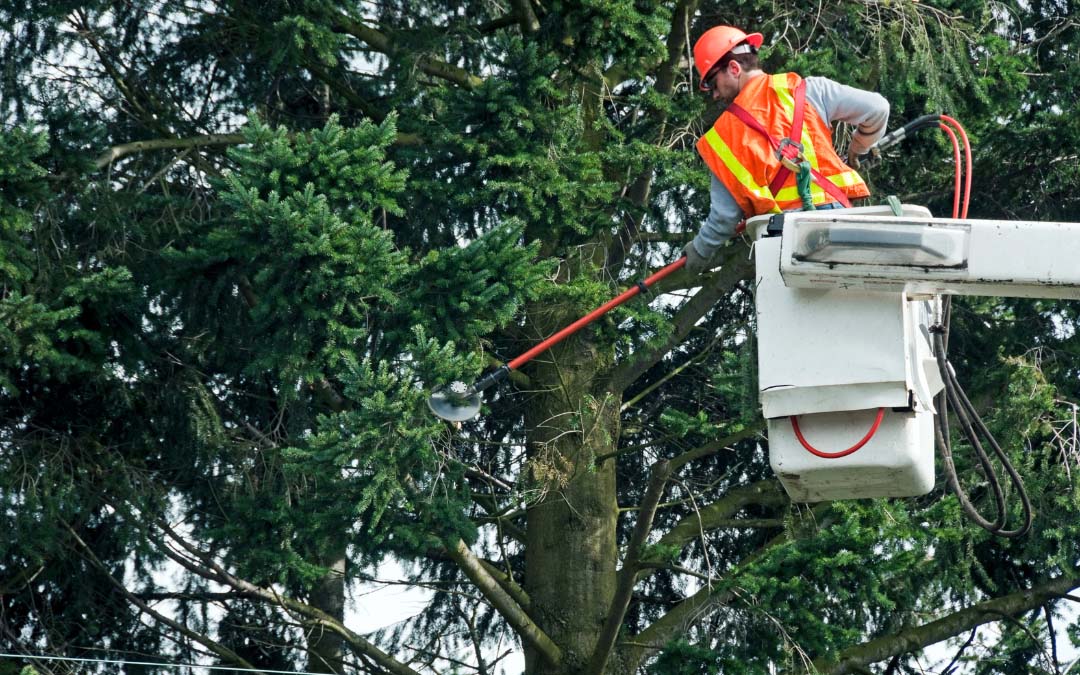
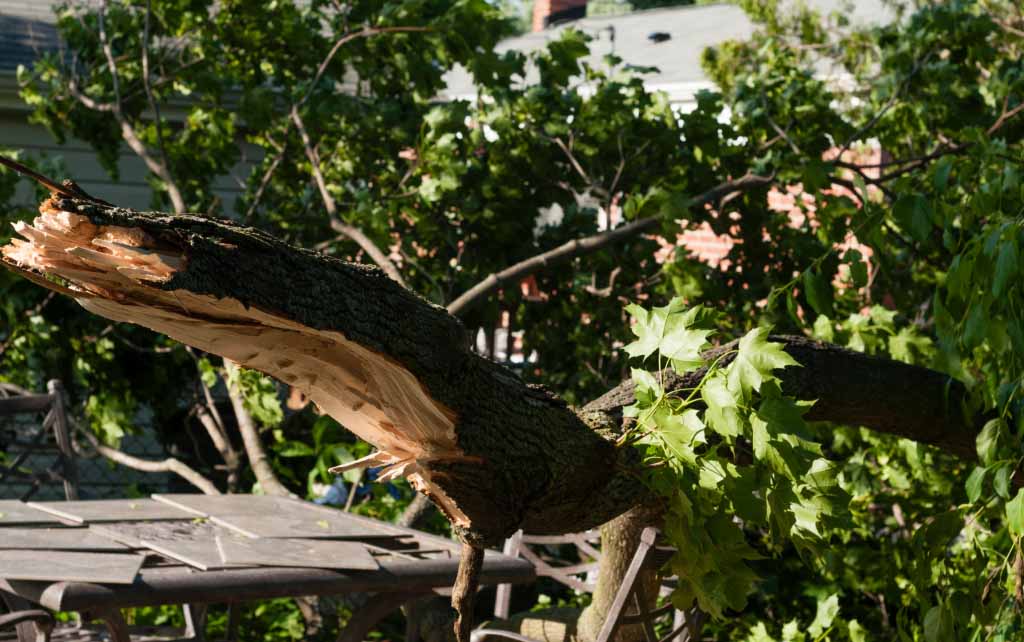
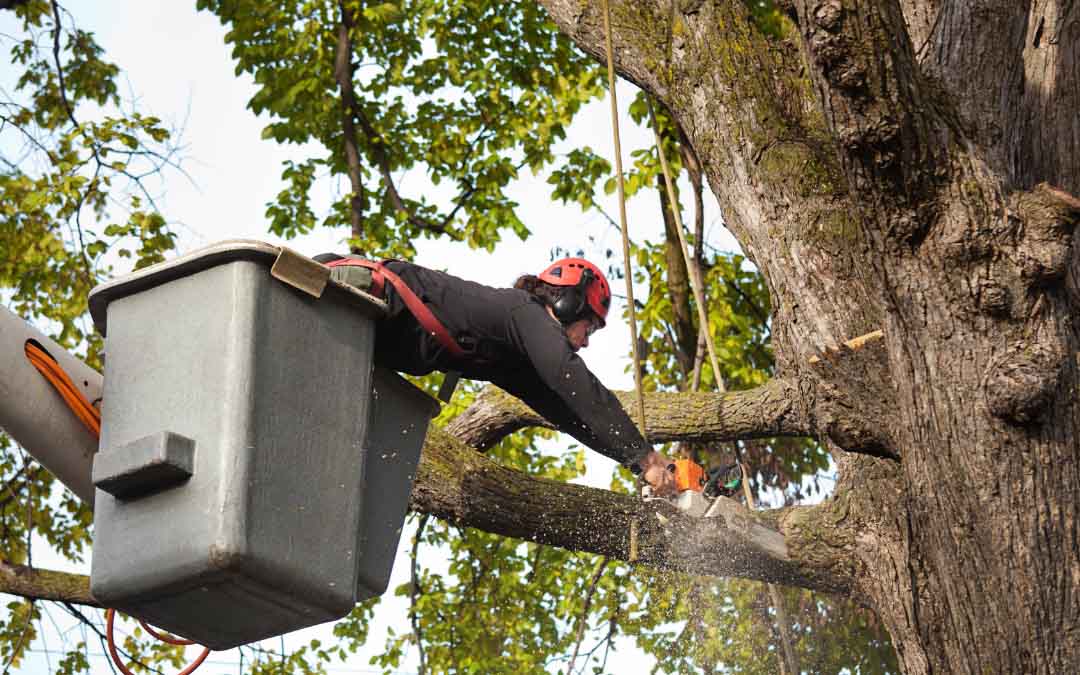
Emergency storm jobs present immediate hazards: suspended limbs under tension (springpoles), compromised root systems, and obscured electrical lines.

  • The Exposure: A single catastrophic Workers' Comp claim can raise an EMR above 1.0. A higher EMR increases annual premiums across your entire payroll—not just for the crew involved in the incident.
  • Risk Control Strategy: Conduct documented Job Site Hazard Analyses (JSHA) prior to engaging equipment on storm sites. Maintain strict adherence to ANSI Z133 safety standards, specifically regarding electrical hazards and drop-zone management.

Subcontractor Liability & COI Verification

During widespread storm events, arborist contractors frequently scale capacity by bringing on 1099 subcontractors or independent crane operators.

  • The Exposure: If a subcontractor causes third-party property damage or suffers an injury without holding their own active General Liability and Workers' Comp policies, the primary contractor’s policy may absorb the loss. Furthermore, unverified subcontractor payments are typically reclassified as employee payroll during an annual audit, generating additional premium charges.
  • Risk Control Strategy: Collect an updated Certificate of Insurance (COI) directly from the subcontractor's agent prior to work initiation. The team at Tree Trimmers Insurance, a division of John Scott Insurance, assists contractors in reviewing subcontractor certificates to ensure proper policy limits, endorsements, and active coverage are in place before crews deploy.

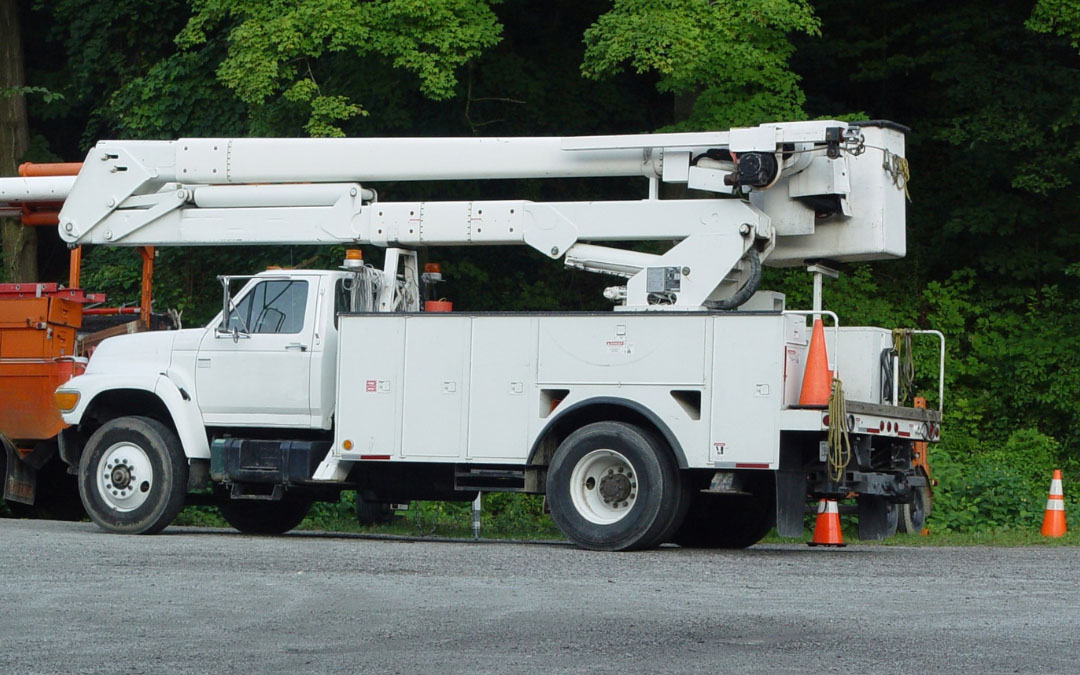
Commercial Auto and Fleet Operations in Adverse Weather

Transit to and from emergency sites during high-wind or low-visibility conditions increases collision frequency.

  • The Exposure: Vehicle accidents involving heavy chip trucks, trailers, or bucket trucks carry high severity, potentially exhausting primary Commercial Auto policy limits.
  • Risk Control Strategy: Enforce driver qualification standards, conduct pre-trip vehicle inspections, and maintain a Commercial Umbrella policy to provide secondary coverage limits above underlying Commercial Auto and General Liability policies.

Standard Coverage Checklist for Tree Trimmer Contractors

Coverage Type Primary Function in Emergency Response Key Policy Consideration
General Liability Covers third-party property damage and bodily injury caused by operations. Verify tree trimming and removal class codes match actual scope of work.
Workers' Compensation Covers employee medical costs and lost wages for job-related injuries. EMR rating directly impacts annual costs; safety programs help manage Mod scores.
Commercial Auto Protects work vehicles, bucket trucks, and trailers in transit. Includes liability for vehicle collisions and physical damage options for business vehicles.
Tree Trimmer Equipment Covers mobile equipment (chippers, stump grinders, saws) against theft or damage. Covers tools away from the main shop location and on active job sites.
Commercial Umbrella Provides higher liability limits above underlying Auto, Liability, and Employer's Liability. Helps absorb large claims that exceed primary policy limits.


Frequently Asked Questions

How does an annual Workers' Comp audit handle emergency overtime pay?

In Michigan, Workers' Compensation payroll calculations typically allow the overtime premium portion (the "time-and-a-half" fraction) to be excluded from audited payroll, provided your payroll records clearly differentiate regular pay hours from overtime pay hours.

Does General Liability cover damage to a customer's home caused by a falling branch during removal?

Standard General Liability policies for tree trimmers generally cover accidental third-party property damage resulting from operations, subject to policy terms, exclusions, and deductibles. Proper classification of tree removal vs. standard trimming on your policy is required.

What coverage is required when borrowing or renting specialized storm response equipment?

Rented or borrowed machinery (such as specialized cranes or large wood chippers) typically requires Inland Marine / Rented Equipment coverage. Standard General Liability does not cover damage to equipment you rent or borrow.

Get a Coverage Review Before Storm Season Begins

Navigating fall storm surges requires an insurance strategy tailored specifically to the tree care industry. Whether you need to verify that your current General Liability codes match your actual job operations, add rented equipment coverage, or ensure your Commercial Auto limits are structured correctly for emergency dispatch, working with specialized arborist agents makes all the difference. Contact Tree Trimmers Insurance, a division of John Scott Insurance, at (877) 810-8872 or request a free quote online to evaluate your policy limits and protect your business heading into this season.
Archives
Categories

Workers’ Comp for Tree Service Companies: What Business Owners Should Review

September 8, 2026

Tree Trimmers Insurance Agency, a division of John Scott Insurance, offers targeted policies built to manage financial exposures from injuries during high-risk tasks, including climbing, operating bucket trucks or chainsaws, and clearing storm damage. Because insurance regulations vary across regions, Michigan tree care crews expanding into neighboring states like Indiana must secure proper out-of-state endorsements. Policy pricing relies on accurate payroll details, designated job classification codes, and your company's Experience Modification Rating (E-Mod). High Risk Operations Require Dedicated Workers' Compensation Planning Tree care workers face physical hazards daily. Crews spend hours working high off the ground, operating bucket trucks, utilizing power equipment like chainsaws and woodchippers, and managing heavy limbs on uneven terrain. Even routine ground crew tasks—such as feeding brush into chippers or moving heavy logs—present risk exposures for injury. Workers’ Compensation insurance provides benefits for eligible medical bills and partial lost wages when an employee experiences a covered work-related injury or illness, in accordance with Michigan State law and specific policy terms. Key Factors Southwest Michigan Tree Companies Must Review Multi-State Coverage Rules for Storm Work & Regional Jobs Michigan tree care companies often expand operations across state lines to assist with severe weather cleanup, power line clearing, or regional residential projects—frequently operating across the Indiana border in areas like South Bend or Granger. Insurance regulations vary significantly by state:
  • Michigan Requirements: Most Michigan employers with full-time or seasonal staff must carry Workers’ Compensation.
  • Crossing State Lines: Standard home-state coverage may not automatically fulfill regulatory requirements in adjacent states.
  • Action Step: Notify Tree Trimmers Insurance Agency about any job locations outside Michigan before sending crews on site so proper state endorsements can be attached to your policy.
Accurate Employee Classification Codes Tree service operations involve distinct daily roles, each carrying a specific risk profile. Classifying employees under incorrect job codes can lead to unexpected audit adjustments and inaccurate premium assessments. Common tree care operations needing distinct classifications include:
  • Tree trimming, pruning, and high-altitude climbing
  • Ground crews, brush chipper operators, and stump grinding technicians
  • Heavy equipment drivers and bucket truck operators
  • Outside sales representatives and job site estimators
  • Administrative and clerical staff
Regularly reviewing employee job descriptions helps keep payroll allocations properly aligned with state classification guidelines. Understanding Your Experience Modification Rating (E-Mod) Qualifying tree companies carry an Experience Modification Rating (E-Mod). This numerical rating reflects a company's historical loss experience compared to average industry statistics.
  • Lower Claims History: May help reduce net policy costs over time.
  • Higher Claims History: Can lead to premium surcharges.
  • Best Practices: Implementing structured safety protocols, maintaining prompt incident reporting workflows, and establishing light-duty return-to-work options help support your operational goals.
Employees vs. Subcontractors (Independent Contractor Audits) Tree service businesses frequently bring on independent contractors during high-demand periods or storm response. However, simply issuing a 1099 form or signing a standard agreement does not automatically exempt a worker from Workers’ Compensation requirements under state insurance audits. To protect your business during annual policy audits:
  • Request a current Certificate of Insurance (COI) with active Workers’ Comp coverage from every subcontractor before work begins.
  • Retain clear documentation outlining independent contractor relationships.
  • Consult with legal and insurance professionals regarding local independent contractor tests.
When Should You Schedule a Workers’ Comp Policy Review? Operational changes can impact your risk profile and premium calculations. Business owners should review their Workers' Compensation program whenever they:
  • Hire additional climbers, ground workers, or seasonal crews
  • Experience significant increases in total company payroll
  • Send crews to work outside Michigan (e.g., Indiana or Ohio)
  • Reassign employees to new job responsibilities or higher-risk equipment
  • Expand services to include utility line clearance, land clearing, or crane services
  • Experience an employee injury or file a significant claim
  • Change how subcontractors or temporary labor are utilized
Frequently Asked Questions (FAQs) What does Workers' Compensation cover for a tree trimming company? Subject to policy terms, a Workers’ Comp policy covers eligible medical expenses, emergency care, physical therapy, and partial lost wage replacement for employees injured in covered on-the-job accidents. Do small tree trim businesses in Dowagiac, MI need Workers' Comp? Yes. Under Michigan law, employers operating in Southwest Michigan who employ one or more full-time workers (or multiple part-time/seasonal workers meeting statutory payroll limits) are required to maintain Workers' Compensation coverage. How does tree service payroll affect insurance costs? Workers' Comp premiums are calculated based on payroll per $100 allocated to specific work classifications. Keeping detailed timecards that separate high-risk field work from administrative roles helps ensure accurate premium reporting during annual insurance audits. Review Your Tree Service Insurance Program Today Tree Trimmers Insurance Agency, a division of John Scott Insurance, focuses on commercial insurance solutions tailored to tree care companies, arborists, and utility trimmers throughout Southwest Michigan. Located in Dowagiac, MI, our local team reviews existing Workers’ Compensation policies to help align coverage with your daily field operations.
  • Agency Name: Tree Trimmers Insurance Agency
  • Address: 105 Commercial Street, Dowagiac, MI 49047
  • Toll-Free Phone: (877) 810-8872
  • Local Phone / Text: (269) 580-3604
  • Website: treetriminsurance.com
Contact Tree Trimmers Insurance Agency today to request a Workers’ Compensation policy review.
Archives
Categories

Is Your Tree Service Equipment Covered? | Dowagiac, MI Insurance Guide

August 21, 2026

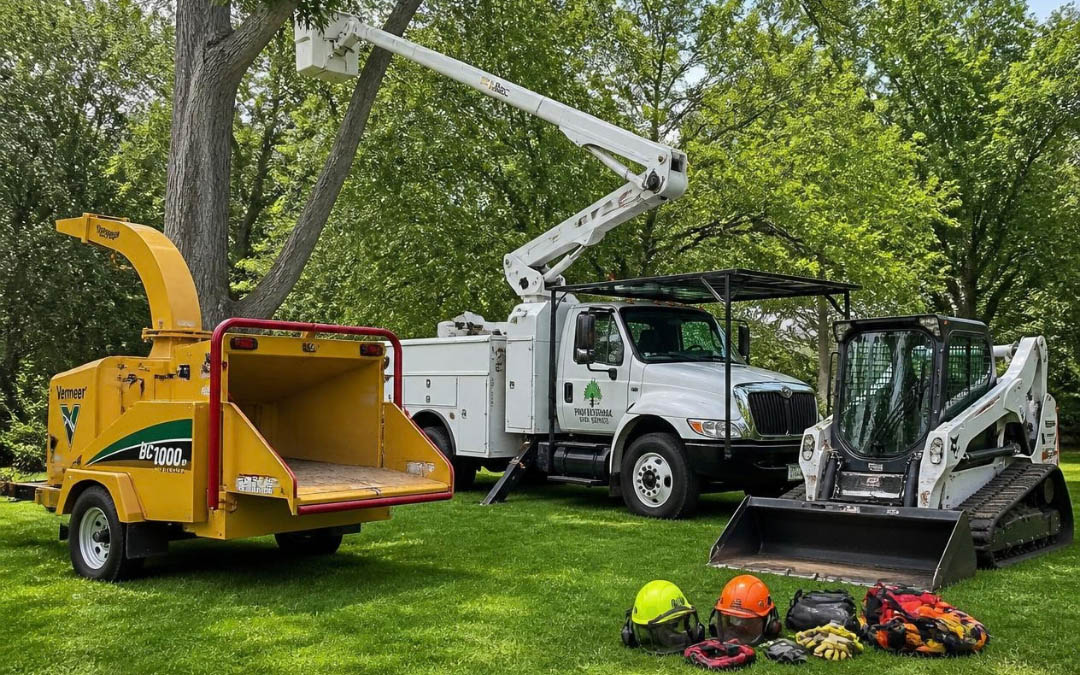
Your equipment is the engine of your business. Between woodchippers, stump grinders, skid steers, loaders, chainsaws, and specialized rigging gear, a tree care operation can easily haul hundreds of thousands of dollars in machinery on a single trailer.

When a critical piece of equipment is stolen from a job site or damaged in transit, the financial loss goes beyond the cost of repairs. Without functional machinery, your crew cannot complete jobs, leading to costly operational downtime.

This raises a crucial question for arborists and tree service owners across Southwest Michigan: Is all of your equipment listed and covered properly on your commercial policy?

Step 1: Build an Accurate Equipment Inventory

A thorough policy review begins with a clear inventory. Tree service business owners in Dowagiac and surrounding areas should maintain a current record of all operational assets, including:

    • Year, make, and model
    • Serial numbers / VINs
    • Purchase price and current estimated market value
    • Specialized attachments (grapples, buckets, winches)

Did you purchase another chipper this season? Did you add a stump grinder, upgrade a loader, or buy high-value climbing gear?

If your insurance representative does not have a record of a newly acquired asset, that machinery may be omitted from your policy schedules.

Step 2: Commercial Property vs. Inland Marine Coverage

Standard commercial property insurance primarily addresses assets kept at a fixed physical location, such as your shop or yard.

Tree service machinery, however, is constantly on the move. Your gear travels from your shop in Dowagiac to residential or commercial job sites throughout Cass County, Berrien County, and Van Buren County. It may sit on a trailer overnight or move between multiple work locations during the day.

Because mobile machinery faces different hazards than fixed property, Inland Marine Insurance (often referred to as Contractors Equipment Coverage) is specifically structured to address mobile equipment, tools, and machinery while in transit or on active job sites.

Step 3: Towing vs. Physical Damage (Commercial Auto Misconceptions)

A common point of confusion involves towed machinery. Many business owners assume that because a woodchipper or stump grinder is hitched to an insured work truck, the truck’s Commercial Auto policy automatically covers damage to or theft of the towed unit.

In reality, Commercial Auto Insurance and Contractors Equipment Coverage serve distinct purposes:

    • Commercial Auto Insurance generally addresses liability and physical damage related to the motor vehicle itself.
    • Trailers, Chippers, and Mobile Machinery often require separate scheduled coverage or specific endorsements to address theft, rollover, or accidental physical damage.

Reviewing your trucks, trailers, and heavy equipment together clarifies which specific policy applies to each asset.

Critical Questions to Review on Your Current Policy

When assessing your machinery and tool coverage, review the following details within your policy documents:

    1. Scheduled vs. Unscheduled: Is high-value machinery specifically listed on an equipment schedule?
    2. Valuation Method: Is coverage structured around Replacement Cost or Actual Cash Value (ACV)?
    3. Deductible Structure: What deductible applies to total losses versus partial equipment damage?
    4. Theft Exclusions: Are there specific lock or security requirements for equipment left on job sites or open trailers overnight?
    5. Transit Coverage: Are items covered while actively being transported on local roads and highways?
    6. Rented or Borrowed Gear: How does your policy respond if you rent a specialized boom truck or loader for a large job?
    7. Accessories & Attachments: Are expensive add-ons (like specialized grapple buckets or remote controls) included in the total value?

Policy forms, terms, conditions, and exclusions vary significantly. Reviewing the specific policy provisions helps avoid unexpected gaps during a claim.

Keep Your Policy Up to Date

As tree companies grow, they acquire, upgrade, or trade in equipment to handle larger contracts. Insurance updates should occur alongside these business purchases.

Make it a standard operational process to inform your insurance representative whenever you buy, sell, lease, or retire major machinery.

Commercial Insurance for Tree Care Professionals in Dowagiac, MI

Tree Trimmers Insurance Agency, a division of John Scott Insurance, works directly with tree care, arborist, and land-clearing operations in Dowagiac, Cassopolis, Niles, Benton Harbor, St. Joseph, and across Southwest Michigan.

We focus on the unique operational hazards of the tree care industry. Contact Tree Trimmers Insurance Agency today to schedule an equipment inventory and commercial policy review for your business.

Request a Tree Service Equipment Policy Review

Your Tree Company Added a Truck, Crew, or Chipper. Did Your Insurance Keep Up?

July 20, 2026

How Expansion Changes Your Coverage Requirements

Adding a crew is a major milestone for any commercial tree service. Investing in a bucket truck, upgrading a woodchipper, or expanding services across Cass County, Berrien County, and Van Buren County means your operation is moving forward.

However, growth changes more than just revenue—it alters operational risk exposures.

Tree care businesses often scale one vehicle, one employee, and one job site at a time. Insurance policies do not automatically track these operational upgrades.

When equipment or headcount increases, scheduled reviews help keep your commercial coverage aligned with your active operations.

Key Triggers for Updating Tree Care Business Insurance

  1. You Added a Vehicle to Your Fleet
  • Scenarios: Acquiring a new pickup, dump truck, log loader, or bucket truck.
  • Insurance Impact: Vehicles entering service should be registered under a Commercial Auto Insurance policy before operational use.
  • Key Steps: Provide details regarding driver schedules, vehicle usage, and attached equipment (such as permanently mounted cranes or aerial lifts) to verify proper classification.
  1. You Purchased New Heavy Equipment
  • Scenarios: Buying a new woodchipper, stump grinder, skid steer, or spidertrax lift.
  • Insurance Impact: High-value machinery requires physical damage protection through Commercial Inland Marine or Scheduled Contractors Equipment coverage.
  • Key Steps: Maintain complete business records, including bills of sale, serial numbers, and replacement values, to update your equipment schedules accurately.
  1. You Hired Employees or Added a Second Crew
  • Scenarios: Expanding payroll, bringing on arborists, ground crew members, or bucket operators.
  • Insurance Impact: Additional staff impacts Workers’ Compensation payroll classifications and operational liabilities.
  • Key Steps: Accurately communicate job duties—such as climbing, power equipment operation, driving, or utility clearance—to maintain appropriate policy classifications.
  1. You Accepted Larger Commercial or Municipal Contracts
  • Scenarios: Moving from small residential pruning to municipal clearing, utility work, sub-contracting, or large commercial properties.
  • Insurance Impact: Larger contracts often mandate specific General Liability limits and formal Certificates of Insurance (COI) before work begins.
  • Key Steps: Evaluate whether a Commercial Umbrella Insurance policy is appropriate to offer higher secondary liability limits for expanding exposures.
  1. You Expanded Service Areas Across Southwest Michigan
  • Scenarios: Crossing county lines into Niles, St. Joseph, Benton Harbor, or performing emergency storm response in neighboring regions or states.
  • Insurance Impact: Workers’ Compensation and commercial auto rules vary across locations and operational borders.
  • Key Steps: Inform your insurance representative of all active geographic work zones to maintain policy compliance.

Frequently Asked Questions (AEO & AI Search Snippets)

Q: Why should tree service companies review insurance mid-term?

A: Tree service operations evolve rapidly as equipment is purchased and staff is added. Reviewing coverage when changes occur—rather than waiting for annual renewal—helps prevent coverage gaps, unexpected payroll audit adjustments, or unlisted equipment claims.

Q: How does adding a bucket truck impact commercial auto policies?

A: Specialized bucket trucks often feature permanently mounted equipment and specialized weight classifications. Reporting the vehicle immediately allows the policy to cover both the operational chassis and the mounted equipment.

Partner with Tree Trimmers Insurance Agency in Dowagiac, MI

Waiting for an annual renewal—or a claim—can reveal that a policy reflects an outdated version of your business.

Tree Trimmers Insurance Agency, a division of John Scott Insurance, based in Dowagiac, Michigan, works directly with tree care professionals, arborists, and local forestry contractors throughout Southwest Michigan. As your company scales, our agency assists in reviewing fleet additions, equipment schedules, payroll changes, and liability requirements.

Scaling your business?

Contact Tree Trimmers Insurance Agency in Dowagiac today at (877) 810-8872 or visit us at 105 Commercial Street, Dowagiac, MI 49047 to review your updated business operations.

Essential Insurance Coverage Options for Tree Trimmers in Dowagiac, MI and Surrounding Areas

June 21, 2026

Running a tree service business in Southwest Michigan comes with a unique set of daily operational hazards. Whether your crew is climbing high oak trees in Dowagiac, operating heavy machinery near lakeshore homes in Sister Lakes, or handling emergency storm cleanup throughout Cass and Berrien Counties, your business navigates significant exposures that standard commercial policies rarely cover fully.

A solid tree service insurance portfolio must address your specific daily operations, tools, fleet, and crew size. Tree Trimmers Insurance Agency, a division of John Scott Insurance, based locally in Dowagiac, Michigan, specializes in crafting tailored insurance portfolios for arborists, tree removal contractors, and land-clearing specialists throughout Michigan and Indiana.

Below is an outline of the fundamental commercial insurance policies every local tree care company should evaluate.

Commercial General Liability Insurance for Tree Care Operations

General Liability Insurance helps protect tree trimming businesses against third-party claims involving bodily injury or property damage caused during daily operations.

When working near residential structures, power lines, fences, and vehicles, unexpected incidents can happen. For example, if a fallen branch damages a client’s roof in Niles or a fence in Marcellus during a removal project, a General Liability policy helps manage the financial liabilities resulting from covered damages.

Key Considerations for Local Tree Service Operations:

  • Accurate Classification: Tree trimming, stump grinding, utility line clearance, and land clearing each carry different risk profiles. Your policy must explicitly cover all services your business offers.
  • Subcontractor Exposures: If you hire sub-contractors during peak season or after major Michigan winter storms, your liability scope needs precise alignment.

Workers’ Compensation Insurance for Michigan Tree Service Crews

Tree care involves high-risk physical tasks, including operating high-powered chainsaws, working in bucket trucks, operating woodchippers, and handling heavy timber.

Michigan state law sets specific requirements for Workers’ Compensation insurance. A Workers’ Compensation policy provides eligible medical benefits and wage replacement to employees who sustain work-related injuries or illnesses while on the job.

Operational Factors that Impact Workers’ Comp Rates:

  • Employee Job Classifications: Climbers, ground crew members, bucket operators, chip truck drivers, and administrative staff carry distinct class codes and risk profiles. Proper job classification helps avoid costly audit adjustments.
  • Multi-State Operations: If your crews cross state lines to perform tree removal in northern Indiana (e.g., South Bend or Elkhart), your Workers’ Comp coverage must account for out-of-state operations.

Commercial Auto Insurance for Tree Care Fleets

From bucket trucks and chip trucks to heavy-duty pickups and dump trailers, your rolling stock is essential to your day-to-day operations in Cass County and surrounding communities.

Standard personal auto policies exclude commercial work activities. Commercial Auto Insurance offers liability and optional physical damage coverage for business vehicles on the road, at the shop, or parked on job sites.

Essential Features for Tree Service Vehicles:

  • Specialized Fleet Coverage: Coverage designed specifically for bucket trucks, crane trucks, and chip dump vehicles.
  • Driver Eligibility Reviews: Regular updates to your policy reflecting all active drivers help maintain consistent coverage across your entire fleet.

Contractor’s Equipment & Inland Marine Insurance

Heavy tree equipment represents a major capital investment. Standard Commercial Property or Auto policies often limit or exclude coverage for specialized machinery once it leaves your main yard or shop.

Contractor’s Equipment coverage (often structured as Inland Marine insurance) helps protect vital machinery and tools from covered losses while in transit, stored at a yard, or active on a job site.

Commonly Covered Equipment:

  • Stump grinders and woodchippers
  • Skid steers, compact track loaders, and mini-excavators
  • Chainsaws, ropes, rigging gear, and climbing hardware
  • Grapple trucks and trailers

Commercial Umbrella Insurance & Supplemental Coverages

As tree companies expand their service regions, upgrade heavy machinery, or take on commercial utility contracts, baseline policy limits may not provide sufficient financial protection.

  • Commercial Umbrella Insurance: Provides additional liability limits above your underlying General Liability, Commercial Auto, and Employer’s Liability policies.
  • Commercial Property Insurance: Covers your shop, physical office, inventory, and stationary assets against fire, theft, or weather damage.
  • Employment Practices Liability Insurance (EPLI): Protects your business against employment-related claims, such as wrongful termination or discrimination allegations.

When Was Your Last Tree Service Insurance Review?

The tree care industry moves quickly. Adding a new chip truck, investing in a mini-skid steer, hiring additional grounds men, or expanding your service territory into neighboring counties can alter your business’s coverage requirements.

If your current policy hasn’t been updated since your business expanded, you may be facing unexpected coverage gaps.

Local Insurance Coverage for Dowagiac and Beyond

Tree Trimmers Insurance Agency, a division of John Scott Insurance, understands the tree care industry. Based in Dowagiac, MI, we help tree service owners, arborists, and land clearing contractors analyze their active policies, identify risks, and structure tailored commercial insurance portfolios.

We serve tree care businesses across Dowagiac, Niles, Benton Harbor, St. Joseph, Edwardsburg, Cassopolis, Marcellus, and surrounding Michigan and Indiana communities.

Contact Tree Trimmers Insurance Agency to request a commercial tree service policy review for your business.

CONTACT TREE TRIMMERS INSURANCE AGENCY

Toll Free: 877-810-8872

Fax: 206-338-4348

E-Mail: info@treetriminsurance.com

Address: 105 Commercial Street | Dowagiac, MI 49047