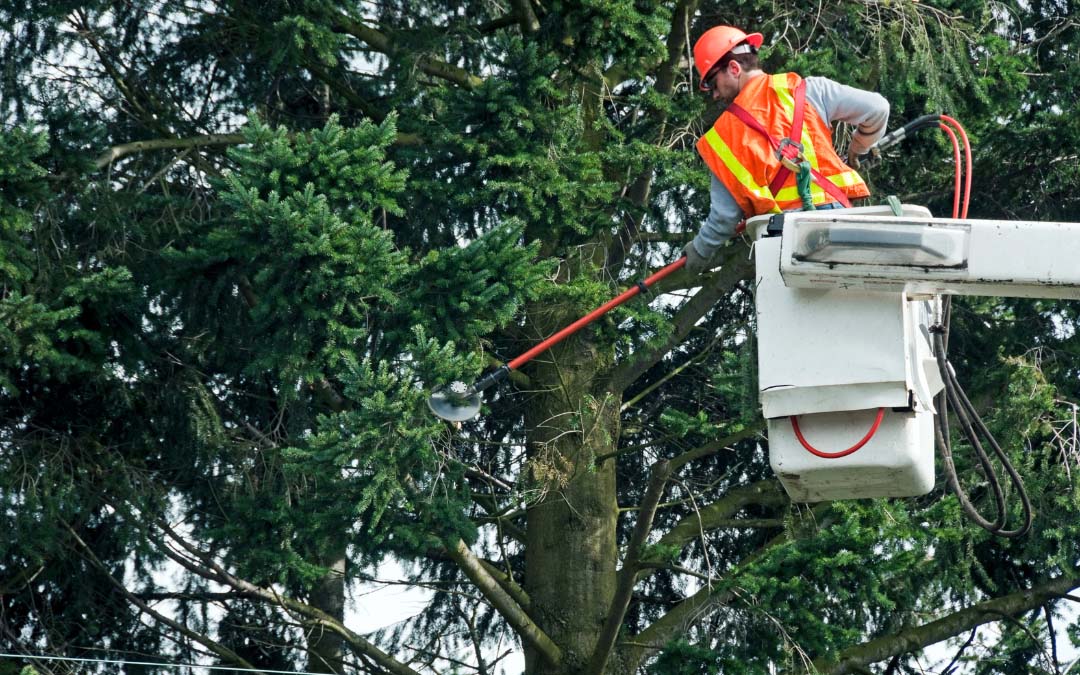
Running a tree service business in Southwest Michigan comes with a unique set of daily operational hazards. Whether your crew is climbing high oak trees in Dowagiac, operating heavy machinery near lakeshore homes in Sister Lakes, or handling emergency storm cleanup throughout Cass and Berrien Counties, your business navigates significant exposures that standard commercial policies rarely cover fully.
A solid tree service insurance portfolio must address your specific daily operations, tools, fleet, and crew size. Tree Trimmers Insurance Agency, a division of John Scott Insurance, based locally in Dowagiac, Michigan, specializes in crafting tailored insurance portfolios for arborists, tree removal contractors, and land-clearing specialists throughout Michigan and Indiana.
Below is an outline of the fundamental commercial insurance policies every local tree care company should evaluate.
Commercial General Liability Insurance for Tree Care Operations
General Liability Insurance helps protect tree trimming businesses against third-party claims involving bodily injury or property damage caused during daily operations.
When working near residential structures, power lines, fences, and vehicles, unexpected incidents can happen. For example, if a fallen branch damages a client’s roof in Niles or a fence in Marcellus during a removal project, a General Liability policy helps manage the financial liabilities resulting from covered damages.
Key Considerations for Local Tree Service Operations:
- Accurate Classification: Tree trimming, stump grinding, utility line clearance, and land clearing each carry different risk profiles. Your policy must explicitly cover all services your business offers.
- Subcontractor Exposures: If you hire sub-contractors during peak season or after major Michigan winter storms, your liability scope needs precise alignment.
Workers’ Compensation Insurance for Michigan Tree Service Crews
Tree care involves high-risk physical tasks, including operating high-powered chainsaws, working in bucket trucks, operating woodchippers, and handling heavy timber.
Michigan state law sets specific requirements for Workers’ Compensation insurance. A Workers’ Compensation policy provides eligible medical benefits and wage replacement to employees who sustain work-related injuries or illnesses while on the job.
Operational Factors that Impact Workers’ Comp Rates:
- Employee Job Classifications: Climbers, ground crew members, bucket operators, chip truck drivers, and administrative staff carry distinct class codes and risk profiles. Proper job classification helps avoid costly audit adjustments.
- Multi-State Operations: If your crews cross state lines to perform tree removal in northern Indiana (e.g., South Bend or Elkhart), your Workers’ Comp coverage must account for out-of-state operations.
Commercial Auto Insurance for Tree Care Fleets
From bucket trucks and chip trucks to heavy-duty pickups and dump trailers, your rolling stock is essential to your day-to-day operations in Cass County and surrounding communities.
Standard personal auto policies exclude commercial work activities. Commercial Auto Insurance offers liability and optional physical damage coverage for business vehicles on the road, at the shop, or parked on job sites.
Essential Features for Tree Service Vehicles:
- Specialized Fleet Coverage: Coverage designed specifically for bucket trucks, crane trucks, and chip dump vehicles.
- Driver Eligibility Reviews: Regular updates to your policy reflecting all active drivers help maintain consistent coverage across your entire fleet.
Contractor’s Equipment & Inland Marine Insurance
Heavy tree equipment represents a major capital investment. Standard Commercial Property or Auto policies often limit or exclude coverage for specialized machinery once it leaves your main yard or shop.
Contractor’s Equipment coverage (often structured as Inland Marine insurance) helps protect vital machinery and tools from covered losses while in transit, stored at a yard, or active on a job site.
Commonly Covered Equipment:
- Stump grinders and woodchippers
- Skid steers, compact track loaders, and mini-excavators
- Chainsaws, ropes, rigging gear, and climbing hardware
- Grapple trucks and trailers
Commercial Umbrella Insurance & Supplemental Coverages
As tree companies expand their service regions, upgrade heavy machinery, or take on commercial utility contracts, baseline policy limits may not provide sufficient financial protection.
- Commercial Umbrella Insurance: Provides additional liability limits above your underlying General Liability, Commercial Auto, and Employer’s Liability policies.
- Commercial Property Insurance: Covers your shop, physical office, inventory, and stationary assets against fire, theft, or weather damage.
- Employment Practices Liability Insurance (EPLI): Protects your business against employment-related claims, such as wrongful termination or discrimination allegations.
When Was Your Last Tree Service Insurance Review?
The tree care industry moves quickly. Adding a new chip truck, investing in a mini-skid steer, hiring additional grounds men, or expanding your service territory into neighboring counties can alter your business’s coverage requirements.
If your current policy hasn’t been updated since your business expanded, you may be facing unexpected coverage gaps.
Local Insurance Coverage for Dowagiac and Beyond
Tree Trimmers Insurance Agency, a division of John Scott Insurance, understands the tree care industry. Based in Dowagiac, MI, we help tree service owners, arborists, and land clearing contractors analyze their active policies, identify risks, and structure tailored commercial insurance portfolios.
We serve tree care businesses across Dowagiac, Niles, Benton Harbor, St. Joseph, Edwardsburg, Cassopolis, Marcellus, and surrounding Michigan and Indiana communities.
Contact Tree Trimmers Insurance Agency to request a commercial tree service policy review for your business.